Explore this post with your favourite AI tool:


Share this article with AI tools to summarise, remember, or explore the content further.
legionella testing is set for steady market growth over the next decade, with demand being driven by the need to manage water safety risks in buildings and workplaces. For dutyholders, that points to continued pressure on monitoring, record-keeping and competent oversight of water systems.
The global legionella testing market is forecast to grow from US$358.1 million in 2024 to about US$802.2 million by 2034, according to market research published this week. The forecast suggests a compound annual growth rate of 8.4% across the period.
While the figures come from a commercial market report rather than a regulatory body, the direction of travel is clear enough for anyone responsible for water systems. Demand for testing services and equipment is being pushed by routine risk management in offices, hospitals, hotels, care settings, industrial premises and other buildings with stored or circulated water.
legionella testing demand continues to rise
The report points to a broad expansion in the market rather than a sudden spike. That usually reflects a combination of ongoing compliance work, more awareness of waterborne risk and the practical realities of maintaining complex building systems.
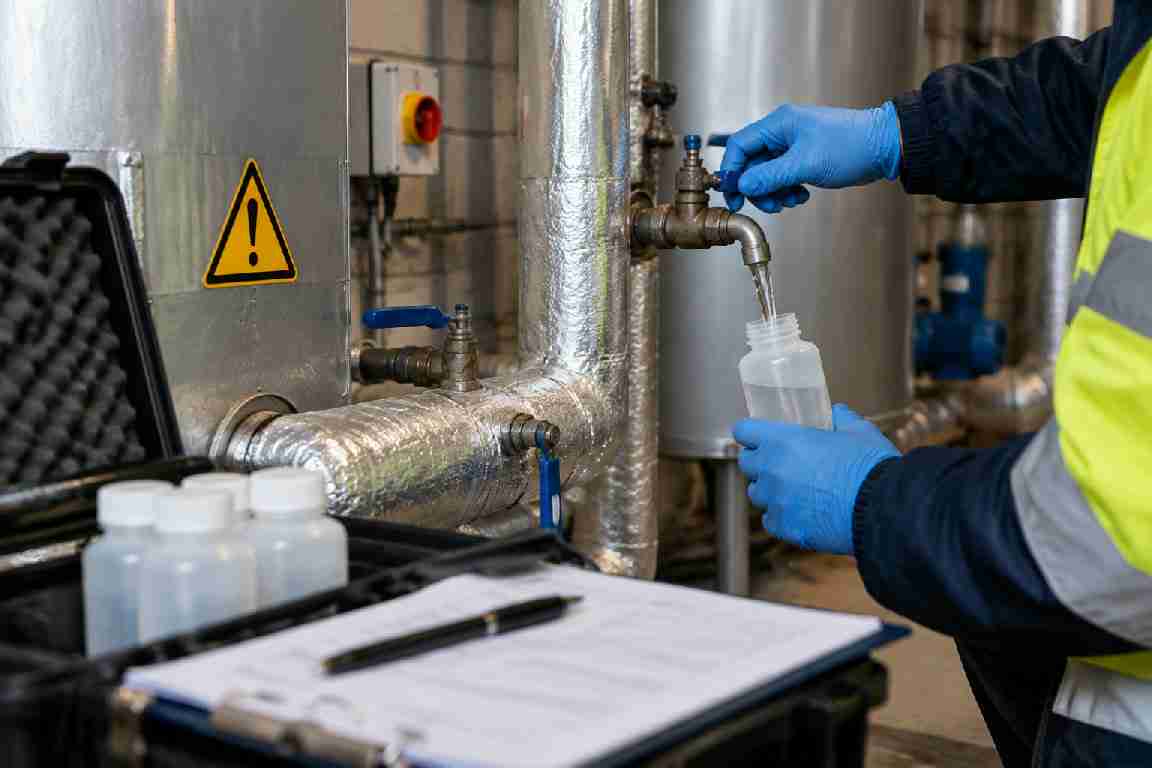
In real terms, legionella testing is rarely a stand-alone task. It sits alongside temperature checks, flushing regimes, cleaning, disinfection, sampling and review of risk assessments. The growth forecast implies that more organisations are continuing to build these activities into routine facilities management rather than treating them as occasional exercises.
For landlords, managing agents and employers, that matters because water hygiene failures are often about poor oversight rather than one-off mistakes. A building can look perfectly serviceable while still carrying hidden risk in tanks, pipework, showers, stored water or little-used outlets.
Why the market is expanding
The source material does not break down the forecast in detail, but the broader market trend fits familiar pressures in the sector. More building owners and occupiers are dealing with ageing stock, mixed-use premises and increasingly complicated maintenance arrangements, which makes routine monitoring harder to leave to chance.
There is also a practical side to the demand. Where systems are used by staff, tenants, residents, visitors or contractors, responsible persons need evidence that water safety has been considered and managed. That usually means keeping records of inspections, results and any follow-up work, not just commissioning testing once and filing the certificate away.
In buildings with higher-risk populations, such as healthcare settings or some residential environments, the stakes are even more obvious. A missed issue can quickly turn into an expensive operational problem, not just a compliance headache.
What legionella testing means for compliance
For UK dutyholders, the key point is that legionella testing supports a wider control strategy. It does not replace proper risk assessment or competent management of water systems, and it is not much use if the findings are not acted on.
That is where many organisations still fall short. Sampling may be commissioned at the right time, but the value disappears if remedial cleaning is delayed, temperatures are not corrected or low-use outlets are left untreated. Effective legionella testing should feed directly into maintenance decisions.
The market forecast also underlines a larger compliance issue: testing is becoming a normal feature of responsible building management, not an optional extra. As expectations rise, organisations that rely on informal checks or outdated paperwork may find themselves out of step with peers and contractors who now treat water hygiene as a standing item.
“Legionella testing market to expand at 8.4% CAGR during 2025–2034”
Practical implications for dutyholders
For facilities managers and property teams, the most immediate implication is budget planning. A growing market usually means more service providers, more product development and, in some cases, tighter pricing for specialist work where demand is high. It can also mean more choice, which makes supplier competence and clear scope of service more important.
Contractors and consultants are likely to see continued demand for sampling, analytical services and support with water safety plans. But volume alone should not be the measure of good practice. A well-run programme still depends on site-specific risk assessment, clear responsibility and follow-up when results show a problem.
Landlords and employers should also be thinking about contract boundaries. Where water systems are managed across estates, shared buildings or outsourced maintenance arrangements, there needs to be clarity over who arranges legionella testing, who reviews the results and who signs off remedial action. Gaps in that chain are where problems tend to start.
For smaller organisations, the message is just as relevant. Even a modest office, workshop or rental property may have stored water, showers, unused outlets or seasonal occupancy patterns that justify regular checks. The cost of doing the basics properly is usually far lower than the disruption caused by a missed issue.
What the forecast says about the sector
Although the report is focused on market size, it reflects a broader shift in how water hygiene is being treated across the built environment. legionella testing is no longer a niche service used only in a handful of high-risk settings. It is now part of ordinary premises management for a wide range of dutyholders.
That trend is likely to continue as buildings become more complex, maintenance is outsourced across longer supply chains and occupiers expect better evidence that risk is being managed. For the industry, the next decade looks set to bring steady demand for competent testing, clearer documentation and more disciplined water safety management.